Rs 60 lakh a year. That sounds like a lot of money, doesn't it?
For most people, an income of Rs 60 lakh is a dream. It represents financial freedom, comfort, and a life without constant money worries. But here is the reality that many high-income earners discover only after they receive their first tax notice: the tax bill on Rs 60 lakh may surprise you.
On a Rs 60 lakh salary, the total tax under the new tax regime for FY 2025-26 comes to Rs 15,52,980, an effective tax rate of about 25.88%.
But what if you used the old regime? The answer: it only helps if your deductions and exemptions are very large.
This guide breaks down exactly how the tax is calculated under both regimes and why regime choice matters more than most people think.
Looking for expert help with income tax 60 lakh, new tax regime, old tax regime, tax calculation, surcharge, section 80C deductions, tax planning? The team at Tax Garden, based in Kondapur, Hyderabad, helps Indian SMEs stay compliant. End-to-end filings, notices, and deadline tracking, all in one place.
The Tax Calculation: New Regime Step by Step
Step 1: Claim the Standard Deduction
Before any tax is calculated, salaried individuals can claim a standard deduction of Rs 75,000 under the new tax regime.
| Particulars | Amount |
|---|---|
| Gross Annual Salary | Rs 60,00,000 |
| Less: Standard Deduction | (Rs 75,000) |
| Taxable Income | Rs 59,25,000 |
While you earn Rs 60 lakh, tax is calculated only on Rs 59.25 lakh.
Step 2: Apply the New Tax Regime Slabs (FY 2025-26)
For FY 2025-26 (AY 2026-27), the new tax regime slabs are as follows:
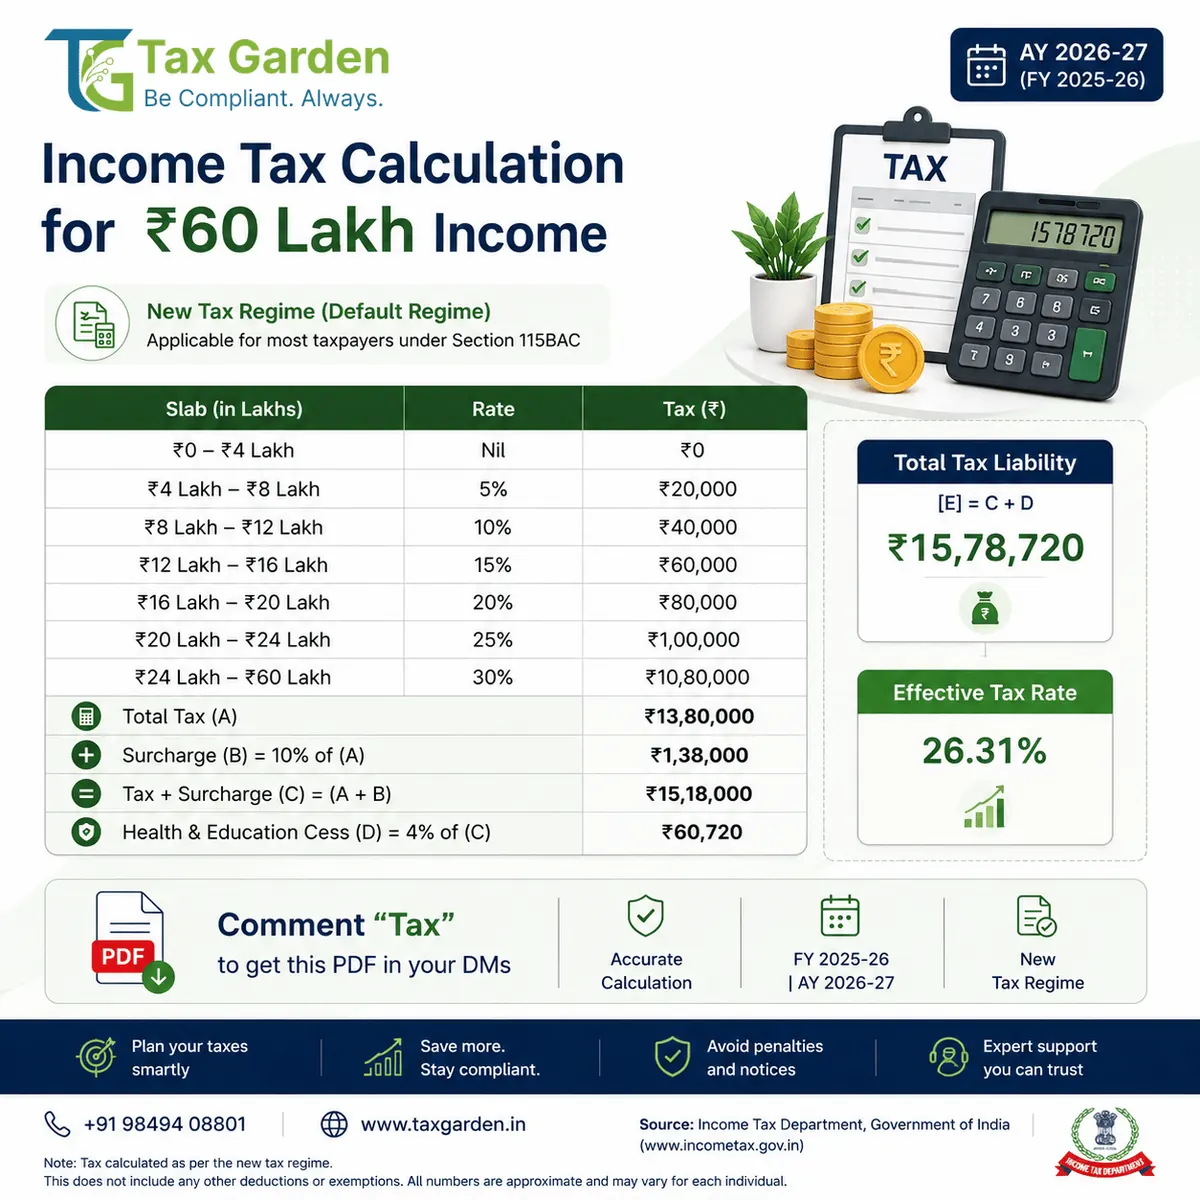
| Income Slab | Rate | Tax Calculation |
|---|---|---|
| Up to Rs 4,00,000 | Nil | Rs 0 |
| Rs 4,00,001 to Rs 8,00,000 | 5% | Rs 20,000 |
| Rs 8,00,001 to Rs 12,00,000 | 10% | Rs 40,000 |
| Rs 12,00,001 to Rs 16,00,000 | 15% | Rs 60,000 |
| Rs 16,00,001 to Rs 20,00,000 | 20% | Rs 80,000 |
| Rs 20,00,001 to Rs 24,00,000 | 25% | Rs 1,00,000 |
| Rs 24,00,001 to Rs 59,25,000 | 30% | Rs 10,57,500 |
| Total Income Tax | Rs 13,57,500 |
Here is the key insight: only the income above Rs 24 lakh (Rs 35.25 lakh in this case) is taxed at 30%. The slab system ensures that different portions of your income are taxed at different rates.
Step 3: Surcharge, the Hidden Tax on High Earners
Once your taxable income exceeds Rs 50 lakh, a surcharge kicks in.
| Income Range | Surcharge Rate |
|---|---|
| Rs 50 lakh to Rs 1 crore | 10% |
| Rs 1 crore to Rs 2 crore | 15% |
| Rs 2 crore to Rs 5 crore | 25% |
| Above Rs 5 crore | 25% (New Regime) / 37% (Old Regime) |
For a Rs 60 lakh income, the surcharge is 10% of the income tax:
| Component | Amount |
|---|---|
| Income Tax | Rs 13,57,500 |
| Surcharge @ 10% | Rs 1,35,750 |
| Tax + Surcharge | Rs 14,93,250 |
Step 4: Health and Education Cess
Finally, a 4% Health and Education Cess is levied on the tax plus surcharge.
| Component | Amount |
|---|---|
| Tax + Surcharge | Rs 14,93,250 |
| Cess @ 4% | Rs 59,730 |
| Final Tax Liability (New Regime) | Rs 15,52,980 |
Effective Tax Rate (New Regime): Rs 15,52,980 ÷ Rs 60,00,000 = 25.88%.
Take Home (New Regime): Rs 60,00,000 - Rs 15,52,980 = Rs 44,47,020
The Tax Calculation: Old Regime with Deductions
Now, let us calculate the same Rs 60 lakh income under the old tax regime, assuming standard deductions.
Step 1: Claim the Standard Deduction (Old Regime)
The old regime allows a standard deduction of Rs 50,000.
| Particulars | Amount |
|---|---|
| Gross Annual Salary | Rs 60,00,000 |
| Less: Standard Deduction | (Rs 50,000) |
| Subtotal | Rs 59,50,000 |
Step 2: Deductions under Section 80C and Other Sections
The old regime allows various deductions that can significantly reduce taxable income:
| Deduction | Limit | Assumption |
|---|---|---|
| Section 80C (PPF, ELSS, Insurance, etc.) | Rs 1,50,000 | Rs 1,50,000 |
| Section 80CCD(1B) (NPS) | Rs 50,000 | Rs 50,000 |
| Section 80D (Health Insurance) | Rs 25,000 - Rs 1,00,000 | Rs 75,000 |
| Section 24(b) (Home Loan Interest, self-occupied) | Rs 2,00,000 | Rs 2,00,000 |
| Total Deductions | Rs 4,75,000 |
| Particulars | Amount |
|---|---|
| Subtotal (after standard deduction) | Rs 59,50,000 |
| Less: Section 80C | (Rs 1,50,000) |
| Less: Section 80CCD(1B) | (Rs 50,000) |
| Less: Section 80D | (Rs 75,000) |
| Less: Section 24(b) | (Rs 2,00,000) |
| Taxable Income (Old Regime) | Rs 55,75,000 |
Step 3: Apply Old Tax Regime Slabs
| Income Slab | Rate | Tax Calculation |
|---|---|---|
| Up to Rs 2,50,000 | Nil | Rs 0 |
| Rs 2,50,001 to Rs 5,00,000 | 5% | Rs 12,500 |
| Rs 5,00,001 to Rs 10,00,000 | 20% | Rs 1,00,000 |
| Rs 10,00,001 to Rs 55,75,000 | 30% | Rs 13,72,500 |
| Total Income Tax | Rs 14,85,000 |
Step 4: Surcharge (Old Regime)
| Component | Amount |
|---|---|
| Income Tax | Rs 14,85,000 |
| Surcharge @ 10% | Rs 1,48,500 |
| Tax + Surcharge | Rs 16,33,500 |
Step 5: Health and Education Cess (Old Regime)
| Component | Amount |
|---|---|
| Tax + Surcharge | Rs 16,33,500 |
| Cess @ 4% | Rs 65,340 |
| Final Tax Liability (Old Regime) | Rs 16,98,840 |
Effective Tax Rate (Old Regime): Rs 16,98,840 ÷ Rs 60,00,000 = 28.31%.
Take Home (Old Regime): Rs 60,00,000 - Rs 16,98,840 = Rs 43,01,160
New Regime vs Old Regime: The Comparison
This is where the analysis gets interesting.
Head-to-Head Comparison
| Metric | New Regime | Old Regime | Difference |
|---|---|---|---|
| Taxable Income | Rs 59,25,000 | Rs 55,75,000 | Old regime benefit: Rs 3,50,000 lower |
| Income Tax | Rs 13,57,500 | Rs 14,85,000 | New regime benefit: Rs 1,27,500 lower |
| Surcharge | Rs 1,35,750 | Rs 1,48,500 | New regime benefit: Rs 12,750 lower |
| Cess | Rs 59,730 | Rs 65,340 | New regime benefit: Rs 5,610 lower |
| Total Tax Liability | Rs 15,52,980 | Rs 16,98,840 | New regime saves Rs 1,45,860 |
| Effective Tax Rate | 25.88% | 28.31% | New regime: 2.43 percentage points lower |
| Take Home | Rs 44,47,020 | Rs 43,01,160 | New regime: Rs 1,45,860 more |
The Verdict: Which Regime is Better?
For this Rs 60 lakh income example with the assumed deductions:
New Regime is better by Rs 1,45,860 per year.
However, this comparison assumes a specific set of deductions in the old regime. The actual benefit depends on:
- How much you can actually invest in Section 80C instruments
- Whether you have a home loan with interest deduction eligibility
- Your health insurance premium amounts
- Your NPS contribution capacity
Scenario Analysis: What If Deductions Increase?
Let us test a scenario where the old regime deductions are higher.
Scenario: High Deduction Case (Old Regime)
Assume higher deductions, including an HRA exemption:
| Deduction / Exemption | Amount |
|---|---|
| HRA exemption, Section 10(13A) | Rs 1,25,000 |
| Section 80C | Rs 1,50,000 |
| Section 80CCD(1B) (NPS) | Rs 50,000 |
| Section 80D (self and family Rs 25,000 + senior citizen parents Rs 50,000) | Rs 75,000 |
| Section 24(b) (Home Loan Interest, self-occupied cap) | Rs 2,00,000 |
| Total | Rs 6,00,000 |
Taxable Income (Old Regime): Rs 59,50,000 - Rs 6,00,000 = Rs 53,50,000
Tax Calculation:
- Up to Rs 2,50,000 at 0%: Rs 0
- Rs 2,50,001 to Rs 5,00,000 at 5%: Rs 12,500
- Rs 5,00,001 to Rs 10,00,000 at 20%: Rs 1,00,000
- Rs 10,00,001 to Rs 53,50,000 at 30%: Rs 13,05,000
Income Tax: Rs 14,17,500 Surcharge @ 10%: Rs 1,41,750 Cess @ 4% (on Rs 15,59,250): Rs 62,370 Total Tax (High Deduction Case): Rs 16,21,620
Effective Tax Rate: 27.03% Take Home: Rs 43,78,380
Comparison: New Regime still wins by Rs 68,640, but the gap narrows. The old regime breaks even only when deductions and exemptions (beyond the standard deduction) reach about Rs 7,69,250. At that level old regime taxable income is Rs 51,80,750, and marginal relief caps tax plus surcharge at Rs 14,93,250 (the tax of Rs 13,12,500 on Rs 50 lakh plus the Rs 1,80,750 earned above Rs 50 lakh), the same as the new regime before cess.
The Surcharge Trap: Why It Hurts High Earners
The surcharge is often overlooked, but it is the primary reason why high-income earners face unexpectedly high tax bills.
| Income Level | Surcharge Rate | Impact on Tax Bill |
|---|---|---|
| Up to Rs 50 lakh | 0% | None |
| Rs 50 lakh to Rs 1 crore | 10% | Adds 10% to your tax bill |
| Rs 1 crore to Rs 2 crore | 15% | Adds 15% to your tax bill |
| Rs 2 crore to Rs 5 crore | 25% | Adds 25% to your tax bill |
Key Point: Under the new regime, tax plus surcharge and cess on a taxable income of exactly Rs 1 crore is Rs 29,51,520 (about 29.5%). At Rs 2 crore it is Rs 66,73,680 (about 33.4%). The marginal rate on income above Rs 1 crore is 35.88% (30% plus 15% surcharge plus 4% cess).
For the Rs 60 lakh example, the surcharge adds Rs 1,35,750 to the tax bill (Rs 1,41,180 including cess on it), about Rs 11,800 a month.
For the next step up, our income tax on Rs 70 lakh new vs old regime comparison works through the slabs, surcharge and cess in the same way.
How to Choose: New Regime or Old Regime?
| Factor | Favors New Regime | Favors Old Regime |
|---|---|---|
| Simplicity | Yes. No deductions to track. | No. Multiple forms and documents. |
| Investment Capacity | Low. You do not invest much in 80C. | High. You invest Rs 1.5L+ in 80C. |
| Home Loan | No or small interest. | Yes, significant interest deduction. |
| HRA Exemption | Not applicable (new regime does not allow) | Yes, substantial HRA exemption available |
| Changing Jobs | Frequent. Difficult to plan deductions. | Stable. Can plan deductions. |
| Tax Bracket | You prefer lower rates over deductions. | You prefer deductions over rates. |
Quick Decision Tree
If you answer YES to most of these:
- You invest Rs 1.5L+ annually in Section 80C (PPF, ELSS, insurance)?
- You have a home loan with interest above Rs 1 lakh per year?
- You buy health insurance for yourself and family?
- Your income is stable and you can plan investments?
Then: run the old regime numbers. At Rs 60 lakh, these four items together (Rs 1.5 lakh 80C, Rs 50,000 NPS, Rs 75,000 80D, Rs 2 lakh home loan interest) still leave the old regime about Rs 1.46 lakh costlier, as shown above. The old regime pulls ahead only with a large HRA exemption or other deductions taking the total past about Rs 7.7 lakh.
If you answer NO to most of these:
- You do not invest much in tax-saving instruments?
- You have no home loan?
- Your health insurance is basic or employer-provided?
- You prefer simplicity over complex deductions?
Then: New Regime is likely better.
Tax-Saving Strategies for Rs 60 Lakh Income
The deductions below are available only under the old regime. At Rs 60 lakh, the old regime marginal rate is 34.32% (30% plus 10% surcharge plus 4% cess), which is the rate used for the savings figures.
1. Maximize Section 80C Deductions
If you opt for the old regime, Section 80C allows up to Rs 1.5 lakh in total across these instruments:
| Instrument | Limit | Benefit |
|---|---|---|
| Public Provident Fund (PPF) | Rs 1,50,000 | Tax-free growth + deduction |
| ELSS Mutual Funds | Rs 1,50,000 | Market returns + deduction |
| Life Insurance | Rs 1,50,000 (combined) | Insurance + deduction |
| National Savings Certificate | Rs 1,50,000 (combined) | Safe returns + deduction |
Savings: Each Rs 1 lakh invested in Section 80C saves Rs 34,320 in tax under the old regime (full Rs 1.5 lakh: Rs 51,480).
2. Use NPS for Extra Deduction
Section 80CCD(1B) provides an additional Rs 50,000 deduction for NPS, over and above the Rs 1.5 lakh limit.
Savings: Rs 50,000 NPS contribution saves Rs 17,160 in tax under the old regime.
3. Health Insurance (Section 80D)
Health insurance premiums are deductible under Section 80D.
| Beneficiary | Limit |
|---|---|
| Self, spouse and children (all below 60) | Rs 25,000 |
| Self, spouse and children (any one 60 or above) | Rs 50,000 |
| Parents (below 60) | Additional Rs 25,000 |
| Parents (60 or above) | Additional Rs 50,000 |
| Maximum (everyone 60 or above) | Rs 1,00,000 |
For a 45-year-old with family and senior citizen parents: Rs 75,000 deduction saves Rs 25,740 in tax under the old regime.
4. Home Loan Interest (Section 24(b))
For a self-occupied home, interest is deductible under Section 24(b) up to Rs 2 lakh a year in the old regime only. The new regime allows no deduction for self-occupied home loan interest.
For a Rs 50 lakh home loan at 8% interest:
- Annual interest: about Rs 4,00,000 (in year 1)
- Deduction allowed (self-occupied): Rs 2,00,000
- Tax savings: Rs 68,640 (at the 34.32% old regime marginal rate)
5. Education Loan Interest (Section 80E)
Interest paid on education loans is fully deductible with no upper limit, for up to 8 years, under the old regime.
Key Takeaways
| Point | Details |
|---|---|
| Rs 60 lakh = Rs 44.5 lakh take-home (new regime) | Tax eats up 25.88% of your income |
| New regime saves Rs 1.45 lakh vs old regime | But only with assumed deductions; may vary based on your actual situation |
| Surcharge at Rs 50+ lakh is a game-changer | Adds Rs 1.35 lakh+ to your tax bill |
| Deductions matter only in the old regime: Rs 1.5L in 80C saves Rs 51,480 | You need about Rs 7.7 lakh of deductions and exemptions for the old regime to win |
| Regime choice can change every year (salaried) | Without business income, you can pick either regime each year in an ITR filed by the due date |
| ITR filing is essential | Salaried taxpayers without business income file by 31 July; a late return attracts a Section 234F fee and, if tax is due, Section 234A interest. |
Where Tax Garden Helps
Tax Garden's ITR filing service helps high-income earners:
- Compute tax under both regimes from your Form 16, AIS and deduction proofs
- File the ITR on time under the regime you elect
- Reconcile TDS with Form 26AS and AIS before filing
- Prepare replies to tax notices on the e-filing portal
Looking for expert help with income tax 60 lakh, new tax regime, old tax regime, tax calculation, surcharge, section 80C deductions, tax planning? The team at Tax Garden, based in Kondapur, Hyderabad, helps Indian SMEs stay compliant. End-to-end filings, notices, and deadline tracking, all in one place.
Sources: Income-tax Act, 1961 as amended by the Finance Act, 2025 (Section 115BAC slabs and Rs 75,000 standard deduction, First Schedule surcharge rates, Section 24(b), Chapter VI-A); Income Tax Department (incometaxindia.gov.in). All figures recomputed for FY 2025-26. Verify current rates, slabs, surcharge thresholds, and deduction limits on incometaxindia.gov.in before acting, as rules may be updated periodically. This article is general information on income tax calculation and not a substitute for professional advice.
Frequently Asked Questions
What is the effective tax rate on Rs 60 lakh salary under the new regime for AY 2026-27?
After the Rs 75,000 standard deduction, taxable income is Rs 59,25,000. Slab tax is Rs 13,57,500, the 10% surcharge adds Rs 1,35,750 and 4% cess adds Rs 59,730, so the total is Rs 15,52,980. That is an effective rate of about 25.88% and a take-home of roughly Rs 44.47 lakh before other payroll deductions.
Is the old regime better than the new regime on Rs 60 lakh income?
Usually not. With Rs 4.75 lakh of deductions (80C, 80CCD(1B), 80D and Rs 2 lakh home loan interest), old regime tax works out to Rs 16,98,840, about Rs 1.46 lakh more than the new regime. Even with Rs 6 lakh of deductions and exemptions the new regime still wins by around Rs 68,600. The old regime wins only if deductions and exemptions, over and above the standard deduction, exceed about Rs 7.7 lakh (marginal relief on the surcharge starts to help as old regime income nears Rs 50 lakh), which usually needs a large HRA exemption.
What is the surcharge on Rs 60 lakh income and why does it matter?
Once total income crosses Rs 50 lakh, a 10% surcharge applies on the income tax, and 4% cess is then charged on tax plus surcharge. On Rs 60 lakh under the new regime the surcharge is Rs 1,35,750. The rate rises to 15% above Rs 1 crore and 25% above Rs 2 crore, which is capped at 25% in the new regime.
Is marginal relief available on the surcharge at Rs 60 lakh income?
No. Marginal relief only helps when income is slightly above Rs 50 lakh, so that the extra tax plus surcharge does not exceed the income earned above Rs 50 lakh. At Rs 59.25 lakh taxable income, the additional tax and surcharge over the Rs 50 lakh level is far less than the Rs 9.25 lakh of extra income, so the full 10% surcharge applies.
Can a salaried person on Rs 60 lakh choose a different regime every year?
Yes. An individual without business income can pick the old or new regime afresh each year while filing the ITR. The new regime is the default, and the old regime can only be chosen in a return filed by the due date, which was 31 July 2026 for AY 2026-27. People with business income must file Form 10-IEA and can switch back only once.
Work with the Trusted Tax & Compliance Services in Kondapur, Hyderabad - Tax Garden for expert GST filing, ITR, TDS, ROC, and startup compliance support.
Frequently Asked Questions: Tax Services in Kondapur & Hyderabad
What makes Tax Garden a preferred GST consultant in Kondapur?
Tax Garden is ISO 9001:2015 certified and backs every engagement with Kavach, our ₹50,000 error-protection cover. Published monthly plans, with the fee shown before you sign up, make us a compliance partner for startups and SMEs in Kondapur's HITEC City corridor.
Why is Tax Garden a trusted tax compliance partner in Hyderabad?
Trust comes from three pillars at Tax Garden. First, transparency: you know the exact fee before you sign up, and it never changes mid-year. Second, certified expertise: our compliance team is qualified, and the firm holds ISO 9001:2015 certification. Third, accountability: Kavach, our unique error-protection plan, covers up to ₹50,000 in service charges for any clerical mistake made by our team.
Is there a reliable tax consultant near me in Kondapur?
Yes. Tax Garden's office is in Kondapur itself (CWS One Building, Hanuman Nagar). You can book an in-person consultation or get everything done fully online via WhatsApp and our client portal. We serve walk-in clients by appointment and remote clients across all of Hyderabad and Telangana.
I want a friendly tax expert who explains things clearly. Is that Tax Garden?
Yes. Every client can reach our team on WhatsApp and gets plain-language explanations of what is filed and why, plus reminders before every deadline. No jargon, just friendly compliance support from Kondapur.
Where is Tax Garden located in Hyderabad?
Tax Garden is located at 4th Floor, South Block, CWS One Building, Hanuman Nagar, Kondapur, Hyderabad, Telangana 500084. We serve clients across Kondapur, HITEC City, Gachibowli, Madhapur, Jubilee Hills, Banjara Hills, and all of Hyderabad.
Can I get GST filing and registration services in Kondapur?
Yes. Tax Garden offers end-to-end GST services from our Kondapur office: GST registration, GSTR-1, GSTR-3B, GSTR-9 annual returns, ITC reconciliation, e-invoicing setup, and GST notice handling for businesses of all sizes in Kondapur and Hyderabad.
Do you file ITR for salaried employees and businesses in Hyderabad?
Yes. Our Kondapur team files ITR for salaried employees, freelancers, consultants, business owners, LLPs, and companies across Hyderabad. We cover ITR-1 through ITR-6 with complete Chapter VI-A deduction reconciliation, AIS reconciliation, and proactive deadline management.
Which areas in Hyderabad does Tax Garden serve?
Tax Garden's Kondapur office serves clients across Hyderabad including HITEC City, Gachibowli, Madhapur, Jubilee Hills, Banjara Hills, Begumpet, Secunderabad, Ameerpet, Kukatpally, Uppal, LB Nagar, and all of Telangana. Most services are available fully online.
What compliance services does Tax Garden offer for startups in Kondapur?
Tax Garden is a compliance partner for startups in Kondapur and Hyderabad's HITEC City corridor. We handle company incorporation, GST registration, TDS filings, payroll, ROC annual filings, director KYC, and annual ITR filing, all under one flat-fee plan.
How does Tax Garden's compliance model compare to traditional hourly accounting services in Hyderabad?
Tax Garden works on flat-fee monthly plans with a dedicated account manager, monthly compliance updates, and WhatsApp communication. Every entry flagged by our AI-assisted workflow is reviewed by our compliance team before filing, and Kavach covers up to ₹50,000 in service charges for clerical or data errors made by our team.